The statements made in these blog postings do not qualify as tax advice. These statements are general comments based on general questions. Your specific facts will impact the application of the law to your situation.
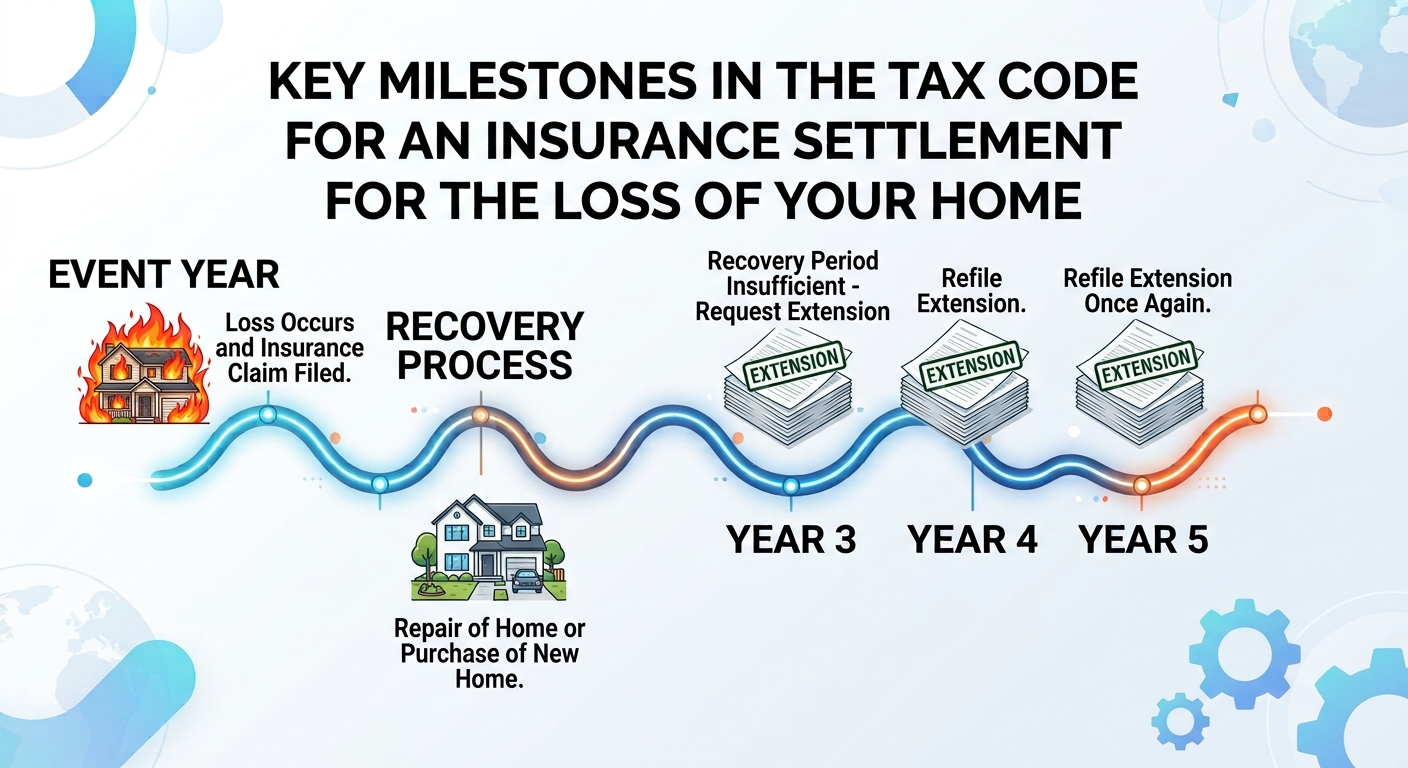
The tax code does establish a timeline for your recovery. There are two timelines, one for losses involving the primary residence of the taxpayer and all other types of losses. The timeline only affects taxpayers, who as a result of compensatory proceeds exceeding the cost basis of the property, have realized a gain. The gain might arise in the same year as the destruction of the property or a subsequent year. The year the destruction occurs is the event year. The first year a gain occurs is the gain year. It does not matter at what time during the gain year that the gain arises. Once the gain year is established, the taxpayer has two more years to complete the recovery process. For a primary residence, substitute four years for two years.
If the statutory recovery period is not sufficient for the taxpayers, it is possible to request an extension. The extension application process involves more than simply filing a form. Extensions can only be granted for one year at a time. Because the extension process can be complicated, it’s best to reach out to a CPA with abundant experience with insurance settlements for the loss of a home.